The Jakarta Post
Please Update your browser
Your browser is out of date, and may not be compatible with our website. A list of the most popular web browsers can be found below.
Just click on the icons to get to the download page.
Popular Reads
Top Results
No results found. Please check your search term and try again
Can't find what you're looking for?
View all search results
Popular Reads
Top Results
No results found. Please check your search term and try again
Can't find what you're looking for?
View all search resultsHow worried should we be about the global economy?
The global economy is entrenched in a cycle of sluggish economic growth, with rates in many countries, particularly the major developed economies, stalling well below 3 percent.
Change text size
Gift Premium Articles
to Anyone
Share the best of The Jakarta Post with friends, family, or colleagues. As a subscriber, you can gift 3 to 5 articles each month that anyone can read—no subscription needed!
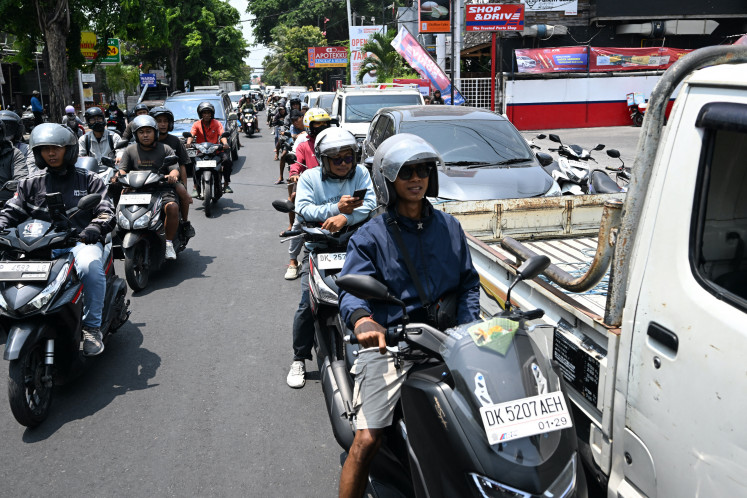
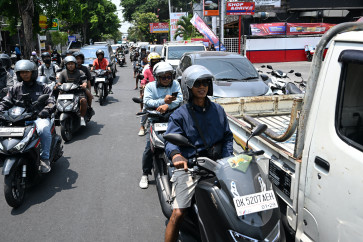
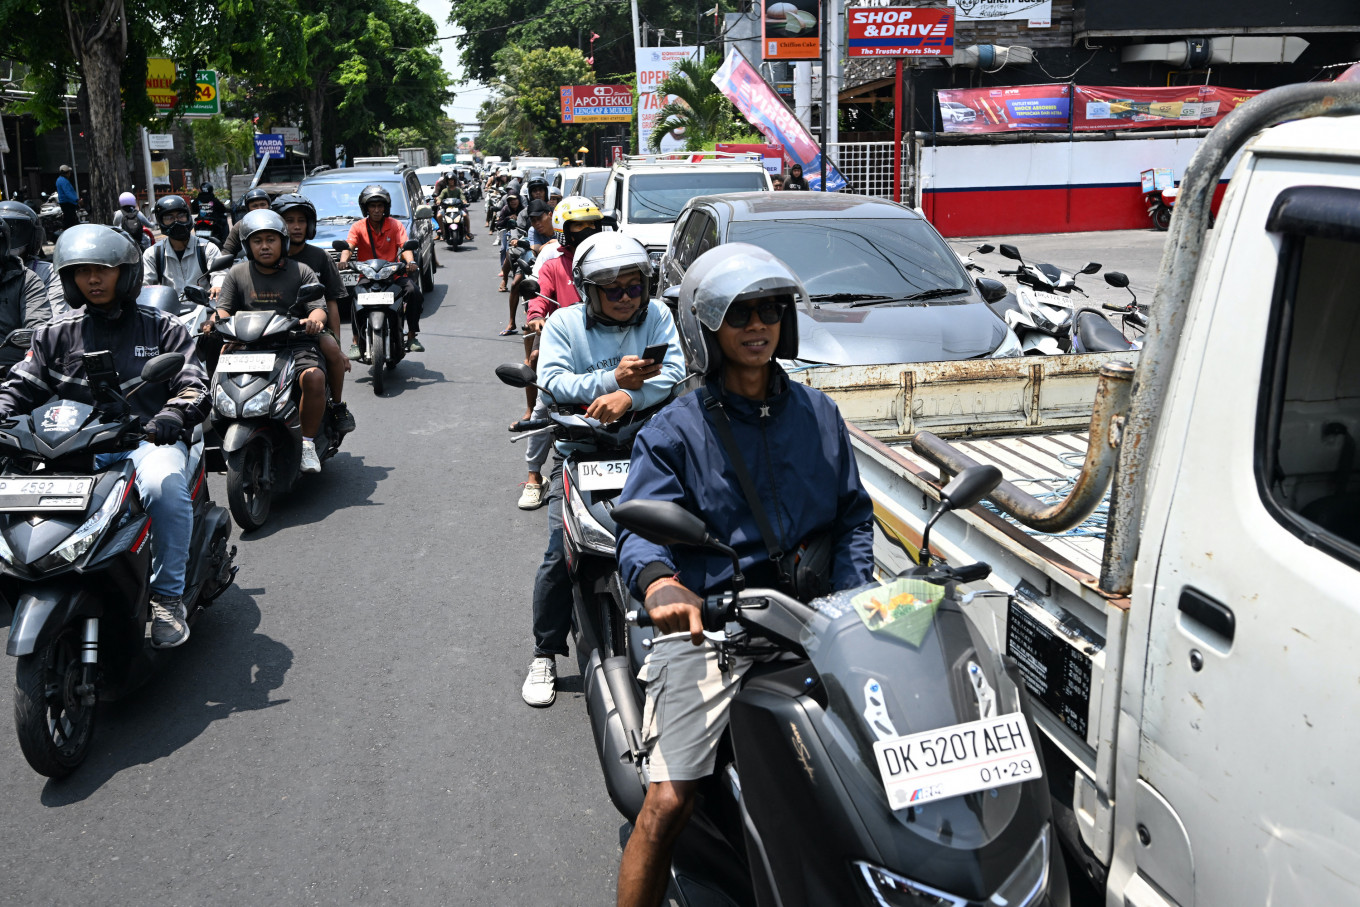 Motorcyclists queue to refuel at a gas station in Denpasar amid a fuel supply shortage in Bali on Oct. 14, 2026. (AFP/Sonny Tumbelaka)
I
t is difficult to remember a time when economies, financial markets, politics and societies were subject to significant volatility and uncertainty simultaneously, let alone to the degree they are today.
The global economy is entrenched in a cycle of sluggish economic growth, with rates in many countries, particularly the major developed economies, stalling well below 3 percent, the level needed to double per capita incomes in a generation.
While the emerging artificial intelligence super-cycle could help offset this trend, in the United States, annual investment appears set to approach 4 percent of GDP by 2032, the technology raises serious, even existential, risks. Industry leaders, including Anthropic’s Dario Amodei and OpenAI’s Sam Altman, have recently called for frontier-AI development to be paused until labs can credibly control their models.
Meanwhile, many economies continue to struggle with inflation, which remains persistently above the 2 percent headline rate targeted by central banks worldwide. Last month, annual inflation in the eurozone hit 3.8 percent, its highest rate in three years, and the United Kingdom’s headline consumer price index reached 3.1 percent in August. In the US, median inflation expectations for the next year rose to 3.9 percent, while holding steady at 3 percent for the five-year horizon.
Some think that inflation is being fueled largely by the Iran war, energy prices have soared since the beginning of this year, and thus amounts to a temporary challenge. But concerns about structural unemployment and job diminution, together with arguably unsustainable public-debt burdens (reaching or exceeding 100 percent of GDP in several advanced economies), suggest that current economic woes will not be overcome so easily.
Public-debt risk is compounded by financial-market developments. For starters, the role of institutional investors that could traditionally be relied upon to hold long-term debt, such as pension funds and insurance companies, is being displaced by hedge funds operating on shorter time horizons. Heightening the risks further, particularly for the US, is the large share of public debt held by foreign governments, including those that, as with China, are not politically or ideologically aligned.

The US has another potential problem: the dollar’s longstanding role as the world’s leading reserve currency and a safe haven in times of crisis is increasingly in doubt. Gold assets have now surpassed US Treasuries in central-bank portfolios. If the dollar does become less dominant, the US can expect its global political clout and economic maneuvering room to decline as well.